Gap Insurance: When It Protects You and When It Does Not
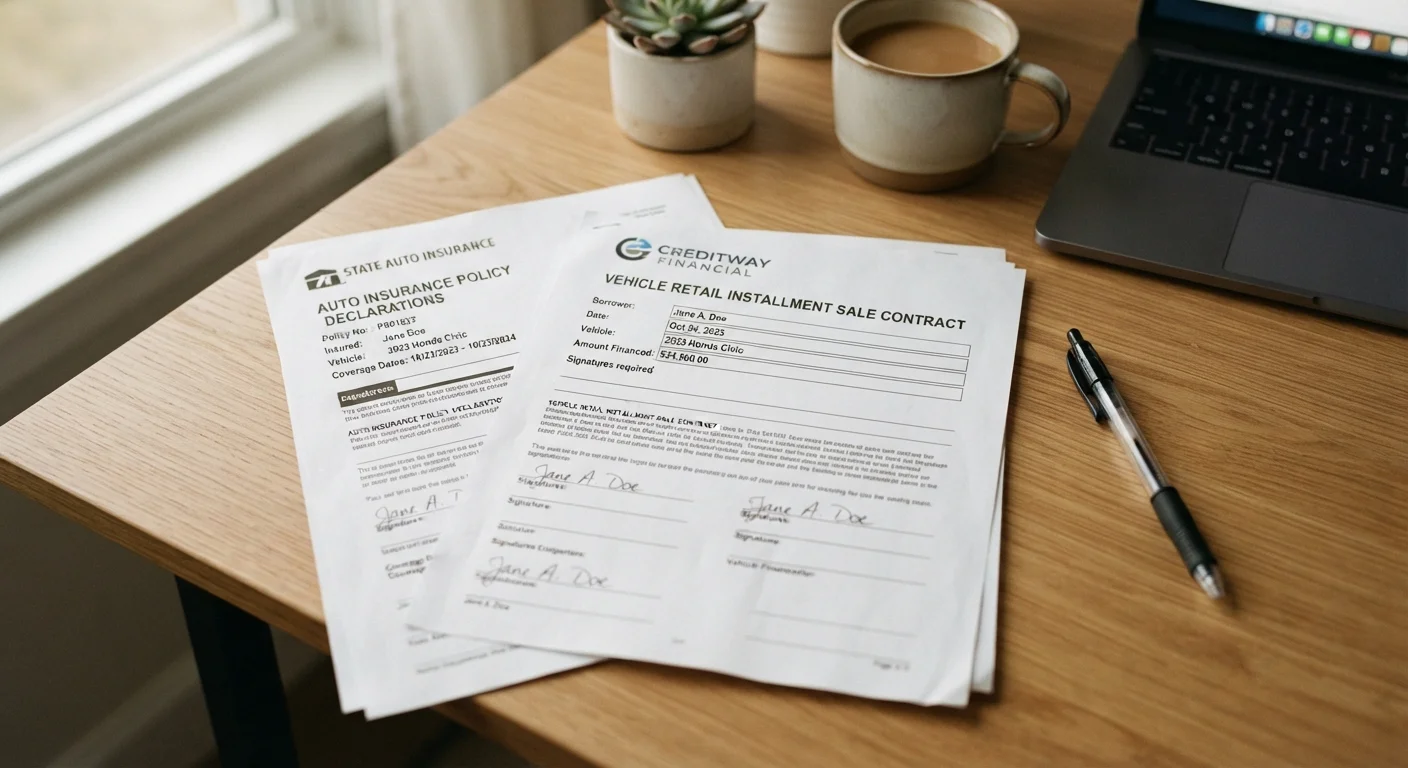
Photo credit: simplefuture.net
In this article
Gap insurance covers the difference between what you owe and what your car is worth. Understand the situations where it is worth carrying.
Key Takeaways
- Gap insurance pays the difference between your loan balance and your car's actual cash value after a total loss.
- It is most useful in the first two to three years of a loan, when depreciation outpaces payoff.
- Drivers who put less than 20 percent down or have long loan terms face the highest risk of being 'upside down'.
- Gap coverage is often unnecessary on leases that already include it or on loans near payoff.
- Prices vary significantly between dealerships and insurers, so comparing quotes matters.
Eliminates out-of-pocket loan balance after total loss
Without gap coverage, a totaled vehicle can leave a driver paying hundreds or thousands of dollars on a loan for a car they no longer own. Gap removes that liability.
Low annual cost when added to an existing policy
Through most auto insurers, gap coverage adds roughly $20 to $40 per year to a policy, making it affordable protection during the highest-risk years of a loan.
Straightforward payout process
When a vehicle is declared a total loss, the insurer calculates the ACV and the gap carrier covers the remaining loan balance, reducing the number of parties the driver must negotiate with.
Covers theft as well as accident total losses
Gap insurance pays on any covered total-loss event, including theft, which standard comprehensive coverage resolves at ACV only.
Dealer-sourced gap coverage is often overpriced
Finance offices at dealerships commonly bundle gap insurance into the loan at prices ranging from $400 to $900, whereas the same protection from an insurer costs a fraction of that amount.
Unnecessary once equity turns positive
Gap coverage provides no benefit once the loan balance falls below the vehicle's actual cash value. Drivers who do not monitor this threshold continue paying for coverage they cannot use.
Does not cover missed payments or fees
Gap policies cover the principal balance difference only. Past-due payments, late fees, and extended warranty costs rolled into the loan are typically excluded from the gap payout.
Requires active collision and comprehensive coverage
Gap insurance pays only after a standard policy settles a claim. Drivers who drop collision or comprehensive coverage lose access to gap protection as well.
What gap insurance actually covers
Gap insurance (Guaranteed Asset Protection) covers the dollar difference between two numbers: what you still owe on your auto loan and what your insurer pays out after a total loss. Standard collision and comprehensive policies pay the vehicle's actual cash value (ACV) at the time of the loss, not what you paid for it or what you owe on it. Because cars depreciate the moment they leave the lot, those two figures can diverge quickly.
For example, if you owe $24,000 on a loan and the insurer values the totaled car at $19,000, a standard policy leaves you with a $5,000 balance on a vehicle you no longer have. Gap insurance covers that $5,000. Some gap policies also cover your deductible, though that varies by product and insurer.
To understand why the gap opens so fast in early loan years, see how vehicle depreciation works. New vehicles can lose 15 to 20 percent of their value in the first year alone, while a standard amortizing loan front-loads interest, meaning the principal balance falls slowly at first.
Pros of carrying gap insurance
Eliminates out-of-pocket loan balance after total loss
Without gap coverage, a totaled vehicle can leave a driver paying hundreds or thousands of dollars on a loan for a car they no longer own. Gap removes that liability.
Low annual cost when added to an existing policy
Through most auto insurers, gap coverage adds roughly $20 to $40 per year to a policy, making it affordable protection during the highest-risk years of a loan.
Straightforward payout process
When a vehicle is declared a total loss, the insurer calculates the ACV and the gap carrier covers the remaining loan balance, reducing the number of parties the driver must negotiate with.
Covers theft as well as accident total losses
Gap insurance pays on any covered total-loss event, including theft, which standard comprehensive coverage resolves at ACV only.
Gap coverage is inexpensive relative to the risk it addresses when purchased through an auto insurer rather than a dealership. Insurer-added gap policies typically cost $20 to $40 per year as a rider on an existing policy, a fraction of the exposure it eliminates. For context, see how gap fits into a broader auto coverage plan.
Cons of carrying gap insurance
Dealer-sourced gap coverage is often overpriced
Finance offices at dealerships commonly bundle gap insurance into the loan at prices ranging from $400 to $900, whereas the same protection from an insurer costs a fraction of that amount.
Unnecessary once equity turns positive
Gap coverage provides no benefit once the loan balance falls below the vehicle's actual cash value. Drivers who do not monitor this threshold continue paying for coverage they cannot use.
Does not cover missed payments or fees
Gap policies cover the principal balance difference only. Past-due payments, late fees, and extended warranty costs rolled into the loan are typically excluded from the gap payout.
Requires active collision and comprehensive coverage
Gap insurance pays only after a standard policy settles a claim. Drivers who drop collision or comprehensive coverage lose access to gap protection as well.
Gap coverage purchased through a dealership finance office is often priced two to five times higher than the same protection added to an existing auto policy. Once the loan balance falls below the vehicle's ACV, the coverage produces no payout and the premium becomes pure cost. Drivers who refinance should also check whether gap coverage transfers or needs to be reissued.
For drivers weighing all the levers on their premium, adjusting your deductible is a separate tool that can offset the cost of adding gap coverage. See also collision vs. comprehensive coverage to make sure the underlying protection gap coverage depends on is already in place.
Situations where gap insurance makes sense
The clearest case for gap coverage is a new vehicle purchase with less than 20 percent down. At that starting point, depreciation in year one can push the loan-to-value ratio well above 100 percent. Long loan terms (72 or 84 months) extend the window of negative equity because principal paydown is slower, leaving the driver exposed longer.
Drivers who rolled negative equity from a previous loan into a new one face immediate exposure. If the previous car was worth $3,000 less than the payoff and that balance was folded into the new loan, the driver starts underwater before depreciation even begins.
Gap insurance also applies to leases, though many lease agreements include it. Lessees should read their contract before purchasing a separate policy to avoid paying twice.
Check your lease contract before buying gap
Many auto lease agreements include gap protection as a standard term, meaning the lessee is already covered if the vehicle is totaled. Adding a separate gap policy on top of a lease that already includes it results in duplicate coverage and wasted premium. Read the lease agreement or ask the leasing company directly before purchasing any additional gap product.
When gap insurance is not worth carrying
Once the loan balance is lower than the vehicle's ACV, the coverage has nothing to pay and can be cancelled. A quick calculation confirms this: request the current payoff amount from your lender and compare it to the vehicle's estimated market value using a publicly available valuation guide. If the payoff is lower, drop the coverage.
Buyers who put 20 percent or more down on a vehicle that holds value well may never enter negative equity territory. In that case, gap coverage adds cost without adding protection. Short loan terms (36 or 48 months) also reduce the negative-equity window considerably.
Drivers of used vehicles purchased at a price already reflecting significant depreciation are less likely to owe more than the car is worth, particularly if the loan term is short. For factors that affect what you pay on your overall policy, understanding why premiums change can help put gap costs in context.
This article is for general informational purposes only and does not constitute personalized financial, insurance, or legal advice. Consult a licensed insurance professional or financial adviser for guidance specific to your situation.
Author
Finance Editorial Team
Finance Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View all articles →