Raising Your Deductible to Lower Premiums: The Trade-Off Explained
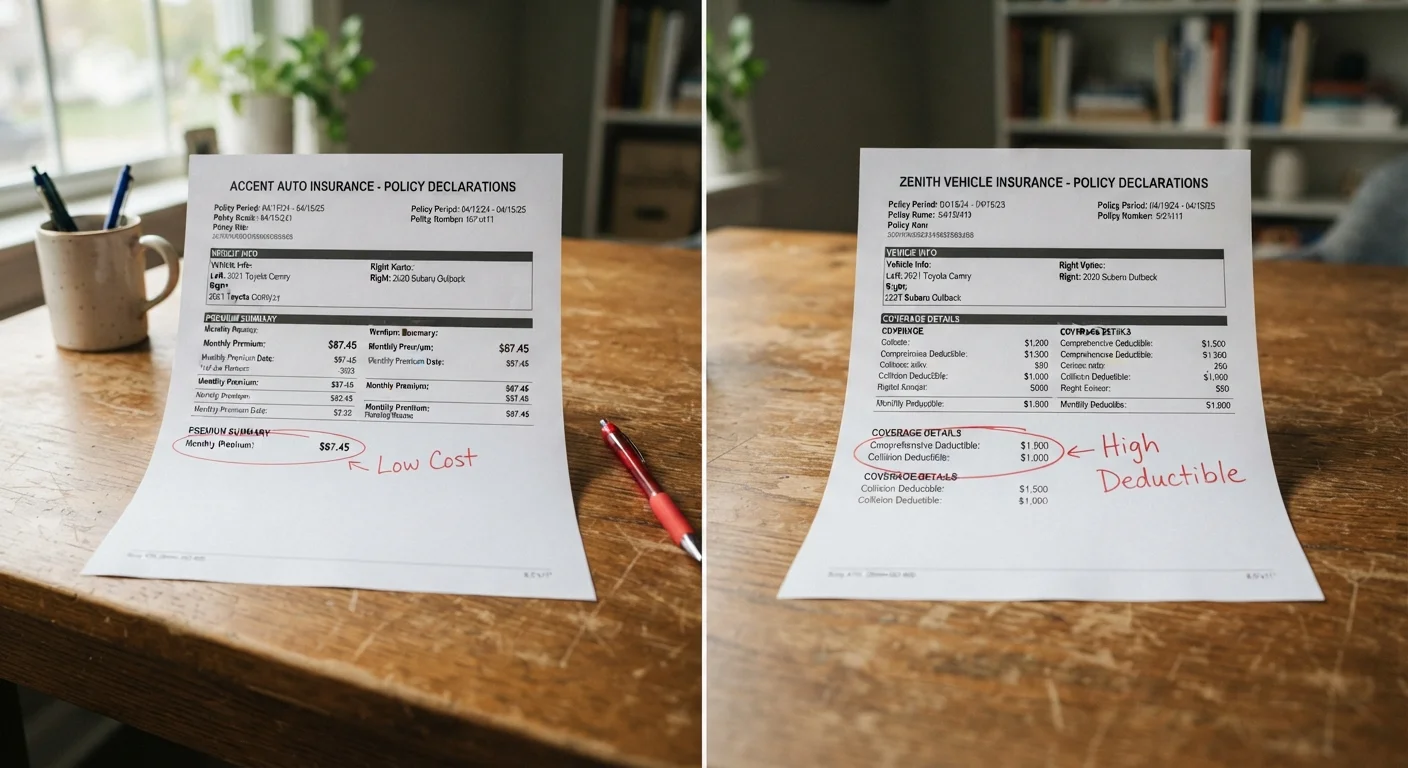
Photo credit: simplefuture.net
In this article
A higher deductible reduces your monthly premium but shifts more risk to you. Learn how to weigh that trade-off for your financial situation.
Key Takeaways
- A higher deductible lowers your monthly premium but increases your out-of-pocket cost after a claim.
- The math only works in your favor if you can actually cover the deductible from savings when needed.
- Low-mileage drivers with clean records often benefit more from a higher deductible than frequent drivers.
- Your lender or leasing company may set a maximum deductible limit on your policy.
- Calculating your breakeven point helps you decide whether the premium savings are worth the added risk.
Lower monthly or semi-annual premium payments
Increasing a deductible from $500 to $1,000 can reduce the collision portion of a premium by 10% to 25%, depending on the insurer and driver profile. Over a year without a claim, that reduction adds up to real savings.
Frees up cash for an emergency savings buffer
Redirecting premium savings into a dedicated account builds a reserve that covers the deductible if a claim does occur, gradually reducing the financial risk of the higher threshold.
Makes sense for low-mileage, low-risk drivers
Drivers who commute rarely or have clean multi-year records have a lower probability of filing a collision claim in any given year, making the actuarial trade-off more favorable.
Reduces small, unnecessary claims
A higher deductible discourages filing minor claims that could raise your rate at renewal. Paying small repairs out of pocket often costs less over time than the premium increase a claim can trigger.
Requires immediate cash after an accident
Repair shops typically require payment before releasing a vehicle. If you cannot access the full deductible quickly, a higher threshold creates a practical financial problem at the worst time.
Unfavorable math for high-mileage drivers
More time on the road means greater exposure to accidents and claims. If your annual mileage is high, the expected out-of-pocket cost over several years may exceed the cumulative premium savings.
Loan or lease agreements may prohibit it
Many auto lenders and leasing companies cap the allowable deductible, often at $500 or $1,000. Choosing a higher deductible without checking your contract could put you in breach of that agreement.
Savings shrink on older, lower-value vehicles
For a vehicle worth $4,000 or less, the premium difference between deductible tiers is often small because the insurer's maximum payout is already limited. The trade-off may not be worth the added exposure.
How the deductible and premium relationship works
Your auto insurance deductible is the amount you pay out of pocket before your insurer covers the rest of a covered claim. Your premium is what you pay periodically, usually monthly or every six months, to keep that coverage active. These two numbers move in opposite directions: raise one and the other tends to fall.
Insurers price policies based on how much financial risk they absorb. A higher deductible shifts more of the first-dollar cost of a claim onto you, so the insurer takes on less exposure and charges less for it. A lower deductible means the insurer steps in sooner, which increases their risk and your premium.
Deductibles apply to collision and comprehensive coverage, not to liability. So this trade-off is only relevant if you carry either or both of those coverages. See what collision and comprehensive actually cover if you are unsure which applies to your policy.
The case for raising your deductible
Lower monthly or semi-annual premium payments
Increasing a deductible from $500 to $1,000 can reduce the collision portion of a premium by 10% to 25%, depending on the insurer and driver profile. Over a year without a claim, that reduction adds up to real savings.
Frees up cash for an emergency savings buffer
Redirecting premium savings into a dedicated account builds a reserve that covers the deductible if a claim does occur, gradually reducing the financial risk of the higher threshold.
Makes sense for low-mileage, low-risk drivers
Drivers who commute rarely or have clean multi-year records have a lower probability of filing a collision claim in any given year, making the actuarial trade-off more favorable.
Reduces small, unnecessary claims
A higher deductible discourages filing minor claims that could raise your rate at renewal. Paying small repairs out of pocket often costs less over time than the premium increase a claim can trigger.
The most direct benefit is immediate savings on your premium. The exact amount varies by insurer, vehicle, location, and driving history, but moving from a $500 to a $1,000 deductible commonly reduces the collision portion of a premium by 10% to 25%, according to general insurer guidance. Over several years without a claim, those savings accumulate.
For drivers who have not filed a claim in several years, a higher deductible also reflects the realistic probability that they will not need to in the near term. If your annual mileage is low and your driving record is clean, you are statistically less likely to file a collision claim in any given year.
The premium savings can be redirected to an emergency fund or set aside specifically as a self-insurance cushion. Some drivers use this strategy to gradually build a reserve that more than covers the higher deductible, which means the risk becomes increasingly manageable over time.
The case against raising your deductible
Requires immediate cash after an accident
Repair shops typically require payment before releasing a vehicle. If you cannot access the full deductible quickly, a higher threshold creates a practical financial problem at the worst time.
Unfavorable math for high-mileage drivers
More time on the road means greater exposure to accidents and claims. If your annual mileage is high, the expected out-of-pocket cost over several years may exceed the cumulative premium savings.
Loan or lease agreements may prohibit it
Many auto lenders and leasing companies cap the allowable deductible, often at $500 or $1,000. Choosing a higher deductible without checking your contract could put you in breach of that agreement.
Savings shrink on older, lower-value vehicles
For a vehicle worth $4,000 or less, the premium difference between deductible tiers is often small because the insurer's maximum payout is already limited. The trade-off may not be worth the added exposure.
The core problem is liquidity. A $1,500 or $2,000 deductible is only workable if you can produce that cash immediately after an accident. Damage to a car often happens without notice, and repair shops typically require payment before releasing a vehicle. If that amount is not sitting in an accessible account, you face a practical crisis on top of the accident itself.
Frequent drivers or those in dense urban areas face a higher probability of a claim each year, which makes the math less favorable. More exposure means the expected value of your out-of-pocket costs rises, and the premium savings may not offset the increased financial risk over time.
There is also the question of loan or lease requirements. If you are financing or leasing your vehicle, the lender may impose a deductible ceiling, often $500 or $1,000. Choosing a higher deductible without checking your loan agreement could put you in violation of your contract. The broader picture of how financing intersects with insurance coverage is worth reviewing: see how deductibles fit into your overall auto policy.
Calculating your breakeven point
Check your loan or lease agreement first
If you are financing or leasing your vehicle, your lender has a financial interest in the car and often sets conditions on your insurance policy, including a maximum deductible. Before adjusting your deductible, read your loan or lease contract or call your lender directly. Violating that term could affect your coverage standing. Once you know the limits your lender sets, you can make a decision within those boundaries.
Before changing your deductible, run a simple breakeven calculation. Subtract the higher-deductible annual premium from the lower-deductible annual premium to find your annual savings. Then subtract those same premium amounts from each other at the deductible level to find the additional out-of-pocket exposure you are taking on.
Divide the extra deductible amount by the annual savings. The result is the number of claim-free years needed to break even. For example, if raising your deductible from $500 to $1,000 saves $150 per year, and you are taking on $500 more risk, you would need to go about 3.3 years without a claim for the math to work in your favor.
That is not a guarantee of outcome, but it gives you a concrete frame for the decision. Drivers with longer stretches between claims generally see the breakeven point arrive faster. Those who have filed multiple claims in recent years will likely find the math tilts against a higher deductible.
If you are also managing add-ons like gap coverage, the combined cost of your policy matters too. Gap insurance has its own cost-benefit logic that is worth weighing separately from deductible decisions.
This article is for general informational purposes only and does not constitute personalized insurance, financial, or legal advice. Consult a licensed insurance professional about your specific coverage needs and policy terms.
Author
Finance Editorial Team
Finance Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View all articles →