What Families Should Know Before Shopping for Auto Insurance
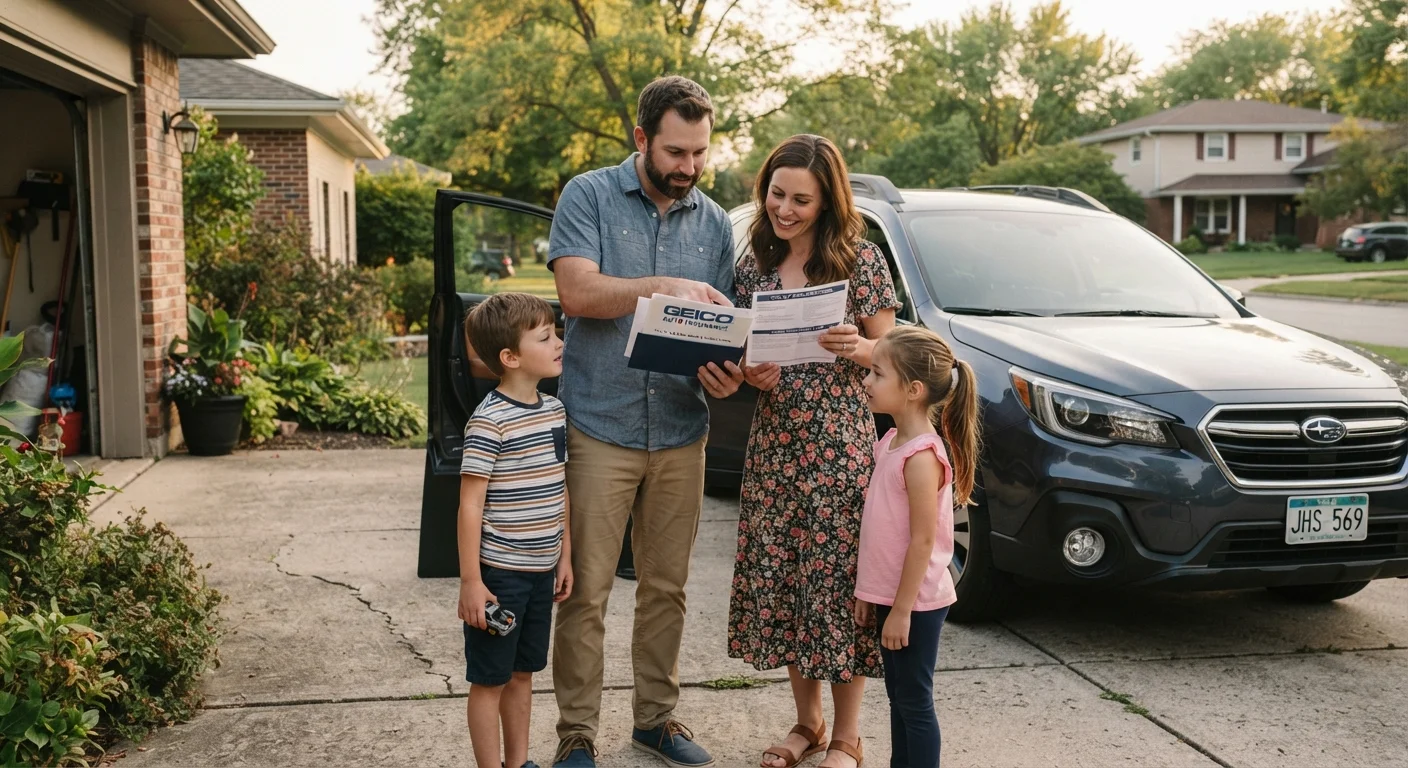
Photo credit: simplefuture.net
In this article
Liability, collision, comprehensive, and deductibles explained in plain English so you can make sense of your coverage options.
Key Takeaways
- Liability coverage pays for injuries or damage you cause to others; it does not cover your own vehicle.
- Collision and comprehensive are separate optional coverages that protect your own car in different situations.
- Your deductible is the amount you pay out of pocket before insurance pays the rest on a covered claim.
- Teen drivers typically raise a household's premium significantly; shopping around can reduce that impact.
- Several factors beyond your driving record affect your rate, including your vehicle, location, and credit history in most states.
Why auto insurance is required and what it actually does
Auto insurance is a contract between you and an insurance company. You pay a regular premium, and in return the insurer agrees to pay certain costs if you have an accident, your car is stolen, or other covered events occur. Almost every state requires drivers to carry at least a minimum amount before they can legally register and drive a vehicle.
The core reason states mandate insurance is financial responsibility. A serious accident can generate medical bills, vehicle repair costs, and legal expenses that most households could not absorb on their own. Insurance spreads that risk so one bad day does not permanently damage someone's finances, whether that is yours or someone else's.
What insurance does not do is cover every possible loss. Policies have limits, exclusions, and conditions. Reading what your policy actually covers, rather than assuming, is one of the most practical things you can do before and after you buy. The finance hub has additional guidance on managing vehicle ownership costs as a whole.
The main coverage types explained
Liability coverage
Insurance that pays for injuries or property damage you cause to someone else in an accident. It does not pay for damage to your own vehicle.
Collision coverage
Coverage that pays to repair or replace your vehicle after it hits another car or object, regardless of who is at fault.
Comprehensive coverage
Coverage that pays for damage to your vehicle from events other than a collision, such as theft, hail, flooding, or hitting an animal.
Deductible
The fixed dollar amount you agree to pay out of pocket when you file a claim before your insurer pays the remaining covered costs.
Premium
The amount you pay to your insurer, usually monthly or every six months, to keep your policy active.
Uninsured/underinsured motorist coverage
Coverage that pays for your injuries or vehicle damage when the driver who caused the accident has no insurance or not enough to cover your costs.
Most personal auto policies are built from several distinct coverages that you can select, and in some cases adjust, separately.
Liability coverage is the foundation. It pays for bodily injury and property damage you cause to other people. It does not pay anything toward your own vehicle or your own injuries.
Collision coverage pays to repair or replace your car after a crash. Comprehensive coverage pays for damage from theft, weather, fire, or animals. These two are technically optional, but if you have a loan or lease on the vehicle, your lender almost certainly requires both.
Uninsured and underinsured motorist coverage (often called UM/UIM) steps in when the driver who caused the accident lacks adequate insurance. Given that a meaningful share of US drivers carry only minimum limits or no insurance at all, this coverage can be important for families.
Medical payments coverage (MedPay) or personal injury protection (PIP, required in no-fault states) pays medical expenses for you and your passengers regardless of who caused the accident.
Lenders often require collision and comprehensive
If you financed or leased your vehicle, your lender most likely requires you to carry both collision and comprehensive coverage until the loan is paid off. This protects the lender's financial interest in the vehicle. Once you own the car outright, those coverages become optional, though they may still be worth keeping depending on your car's value.
How deductibles affect what you pay
Your deductible is the amount you pay out of pocket on a covered claim before the insurer pays the rest. Deductibles typically apply to collision and comprehensive coverage, not to liability.
Choosing a higher deductible lowers your premium because you are taking on more of the financial risk yourself. A lower deductible means higher premiums but less out-of-pocket cost when you file a claim.
A practical way to think about this: if you raised your deductible from $500 to $1,000 and saved $150 a year in premiums, you would need roughly three and a half years of claim-free driving before the savings offset the extra $500 you would owe if something happened. Whether that trade-off makes sense depends on your household's cash reserves and how comfortable you are absorbing a larger unexpected cost.
State minimums may leave you exposed
The minimum liability limits required by your state are often well below the actual costs of a serious accident. Medical bills and vehicle repairs can exceed those limits quickly. If a judgment exceeds your coverage, you may be personally responsible for the difference. Consider your household's assets when deciding how much liability coverage to carry.
Factors that shape your premium
Insurers use a combination of factors to calculate your rate. Your driving record carries significant weight, but it is far from the only input.
- Your vehicle's make, model, age, and safety ratings affect both collision and comprehensive rates.
- Where you garage the car matters. Urban areas with higher accident rates or theft rates typically produce higher premiums than rural zip codes.
- In most states, your credit-based insurance score is a permitted rating factor. States including California, Hawaii, and Massachusetts prohibit or limit this practice.
- Your coverage limits and deductible choices directly affect what you pay.
- Your household's claims history over the prior three to five years is usually reviewed.
For a deeper look at why rates change over time, including factors outside your control, see what drives premium increases.
Get quotes with consistent coverage levels
When comparing quotes from different insurers, use identical coverage limits and deductibles across each quote. A lower premium that comes with lower limits is not a true apples-to-apples comparison. Write down the numbers from your current policy before you start so you have a baseline.
What families with multiple drivers should consider
Households with several drivers, particularly those with a teen or young adult on the policy, face some specific decisions.
Teen drivers raise premiums substantially because their accident rates are higher across the board. Completing a recognized driver education course or maintaining a qualifying grade point average may make a household eligible for discounts that offset part of that increase. Ask specifically about those options when shopping.
Adding a young driver to an existing household policy is generally less costly than that driver buying a separate policy. However, if the young driver has a poor driving record, keeping them on a shared policy could raise rates for the entire household.
Multi-car households should compare the cost of insuring all vehicles under one policy versus separate policies. Bundling is common, but it is not always the lower-cost option, particularly if one vehicle has a very different risk profile than the others.
For context on how insurance fits into the broader cost of owning a vehicle, the annual ownership cost reference breaks down typical expenses by vehicle type. If you are also financing your vehicle, understanding auto loan terms covers the financial side of that decision.
This article is for general informational purposes only and is not financial or insurance advice. Coverage requirements, rating factors, and regulations vary by state. Consult a licensed insurance professional for guidance specific to your situation.
Frequently Asked Questions
Author
Auto Editorial Team
Auto Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View all articles →