What to Check Before Signing a Car Financing Agreement
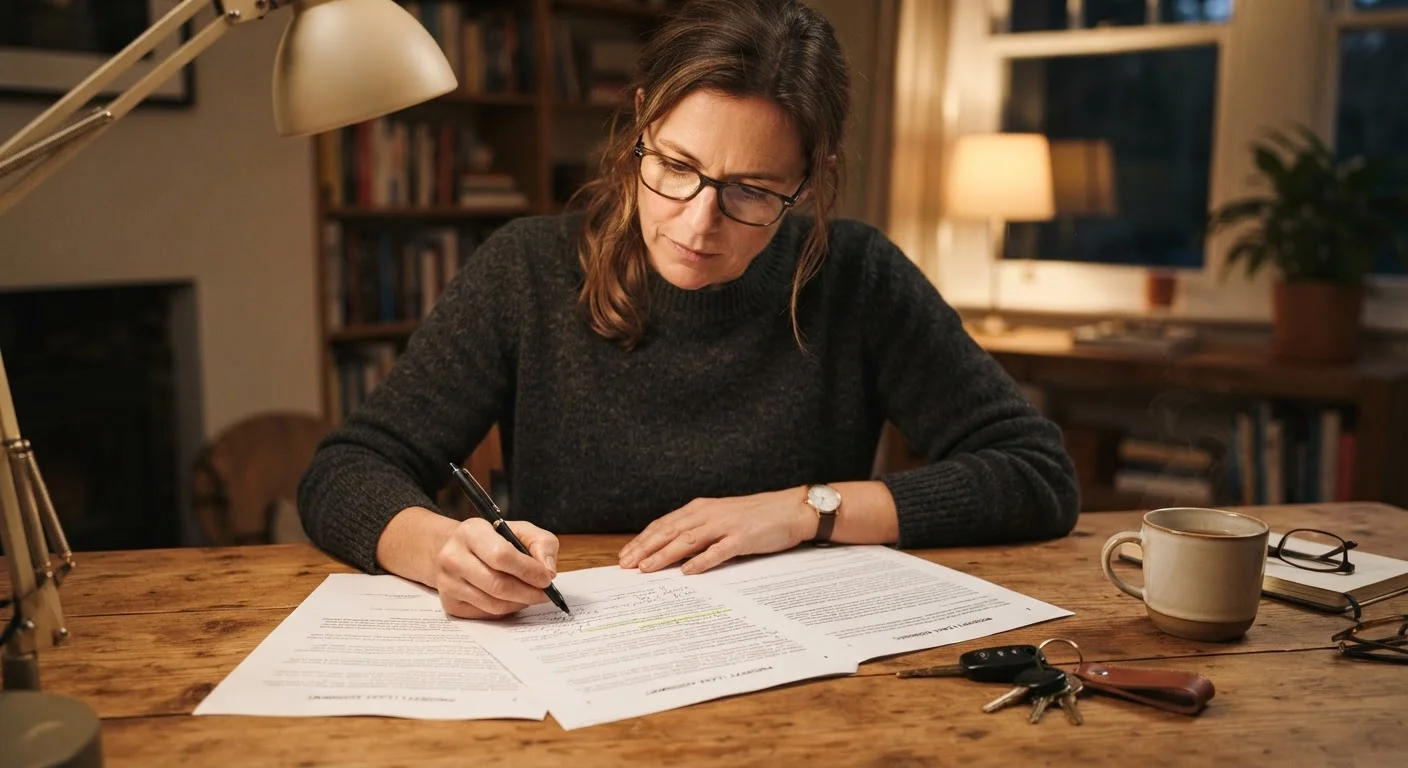
Photo credit: simplefuture.net
In this article
A practical pre-signing checklist covering interest rate, loan length, fees, and add-ons so you understand every line before you commit.
Key Takeaways
- The APR, not just the monthly payment, determines how much a loan actually costs you.
- Loan term length directly affects total interest paid, often by thousands of dollars.
- Add-on products like extended warranties and GAP insurance are negotiable and sometimes unnecessary.
- Fees buried in the contract can significantly raise the effective cost of borrowing.
- You have the right to read and question every line before signing anything.
Why the contract deserves more than a quick scan
A car financing agreement is a legally binding document that can affect your budget for five to seven years. Dealership finance offices move quickly, and the paperwork is dense. Missing one clause about prepayment penalties or a bundled product you did not ask for can cost hundreds or thousands of dollars over the life of the loan.
This checklist walks through what to verify before you put pen to paper. If any term is unfamiliar, our plain-English guide to auto loan terms covers the vocabulary you need going in. For a broader look at how APR and loan length interact with your monthly payment, see our breakdown of APR, loan terms, and monthly payments.
Loan cost basics
Fees and charges
Add-on products
Contract accuracy and terms
Tools that help you review with confidence
You do not need specialized software to audit a financing agreement, but a few resources make the process faster and more accurate.
Online loan amortization calculator
Enter the loan amount, APR, and term to see a full payment schedule and the exact total interest you will pay.
Bank or credit union pre-approval letter
Provides a benchmark rate to compare against the dealer's offer before you sign.
State DMV fee schedule
Lets you verify that title, registration, and any state-mandated fees in the contract match official figures.
Consumer Financial Protection Bureau (CFPB) auto loan resources
Free government-published guides explaining your rights as a borrower during the auto financing process.
One habit worth building: run any rate you are offered against quotes from at least one bank or credit union before you sign. Rate shopping within a short window (typically 14 to 45 days, depending on the scoring model) generally counts as a single inquiry on your credit report. Our article on credit score myths and car loans explains how that process actually works.
What to do if something looks wrong
If a number in the contract does not match what was quoted verbally or in a written offer, stop. Ask for a corrected document before signing. Verbal assurances do not override what the contract says; only the signed agreement is enforceable.
Do not sign a contract with blank fields
Any blank line in a financing agreement is a risk. A blank field can be filled in after you sign, potentially changing the terms you agreed to. Cross out or mark 'N/A' in every blank space before signing, and keep a complete copy of the final document. If the finance office says blanks will be filled in later, that is a reason to pause.
Before you drive off the lot, confirm that you have a complete, signed copy of every document you were given. File it somewhere you can retrieve it easily if a dispute arises later. If you are also shopping for coverage at the same time, understanding your insurance options is a useful next step once the loan paperwork is settled.
This article is general financial information and educational in nature. It is not personalized financial, legal, or tax advice. Consult a qualified financial adviser or attorney for guidance specific to your situation.
Author
Finance Editorial Team
Finance Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View all articles →